US or Canadian – VOO or VFV?

The Currency Balance

Which currency should we invest in, Canadian or US dollars?

In this example, we’ll compare Vanguard’s US listed & US dollar denominated ETF (VOO), against the Canadian listed & Canadian dollar denominated equivalent (VFV) from Vanguard Canada. Imagine investing $10k back in 2012 in each of these ETFs. Conveniently, the Loonie & the greenback were approximately equal back then. One Canadian dollar was worth one US dollar. That means the $10k investment was of equal value, regardless of the currency.

With all dividends reinvested, here’s what the performance has looked like since then …

VOO vs VFV 2012 to 2025

By March 2025, VOO grew from $10k to $52k, in American dollars. While VFV soared to about $73k, in Canadian dollars. VFV looks like the big winner. But it’s not.
Back then the currencies were at par. By the end of this chart, it costs $1.44 Canadian to buy one US dollar. If we sold off VFV at the end & converted the proceeds to US dollars, we’d have a bit less than $51k American. pretty close to the US dollar value of VOO. Similarly, if we sold all our VOO holdings & converted those US dollars to loonies, we’d have almost $75k Canadian. Bottom line is that they’re about the same. We’re only looking at about a fifteen hundred dollar (Canadian) difference in total return, with the American listed VOO coming out slightly ahead.

VOO should come out slightly ahead. There a few reasons for that, including the following …

1. It has the lower fund fee of 0.03%, compared to the 0.09% fee of VFV in Canada.
2. While it all happens inside the ETF, VFV loses a little of the dividend payout due to the 15% dividend withholding tax that the IRS (the US equivalent to the CRA) collects. This happens regardless of the account the Canadian listed ETF is held inside.
3. Though ETFs can do currency exchange at better rates than the typical DIY investor, there might be some additional currency exchange drag on VFV too.

If the fund fees were the same, if currency exchange didn’t have any fees, & if there were no dividend withholding taxes, the performance of the two ETFs would be practically identical. The apparent outperformance of VFV in the chart above is mainly due to the declining value of the Canadian dollar against the US dollar over that 12 year period. Both funds grew similarly in real value (as they should, since they both hold the same stocks). But VFV grew “extra” Canadian dollars over that time, in line with the increasing real value of the stocks inside the EFT. This compensated for the Canadian dollar falling in value against the US dollar. If the reverse had happened, & the Canadian dollar had gained strength against the US dollar over this time, VFV’s numbers would have lagged VOO on the chart. It would have “looked” worse. But, once you convert the currency in either direction, both would have looked pretty much the same again.
That said, there are some pros & cons with either choice.

If you have a bunch of US dollars already & you want to invest these greenbacks inside an RRSP account, VOO would be the better choice. It may not always be this way going forward but, under the current agreement between Canada & the US (& as it was over this timeline), the RRSP account shelters the investor from the dividend withholding tax that would otherwise apply to US based ETFs. On the flip side, if you don’t already have US dollars, you’ll have to pay currency conversion fees. Or learn the Norbert’s Gambit technique to minimise the currency conversion costs. If you want to avoid that currency conversion work, the outcome resulting from sticking with VFV is still pretty good. Particularly when investing outside a registered retirement account, where neither fund can avoid the withholding tax. That would bring the results a little closer together. It is worth noting that the bigger the investment, & the longer the time invested, the greater the potential impact. The $1,500 difference on this $10k investment example, would have been $15,000 on a 100k investment. You can do the math for a million dollar investment as your portfolio grows! And, for a more precise comparison, you’ll need to figure out the impact of currency exchange costs, back & forth, on the end result too.

I’ve ignored some other critically important tax wrinkles (there are some potentially significant exposures here) that come with foreign investing during the course of this comparison, so be sure to consult a tax specialist if you want to invest on exchanges outside of Canada. There are tax reporting requirements with the CRA above a certain value of foreign owned investments, for example. There are also potential IRS tax reporting requirements. And perhaps even US tax liabilities along the way. There’s a lot to learn. And if you don’t know, you’d be well advised to check with a professional advisor to help you figure out your US & foreign investing strategy. In addition, the outcomes may require the inclusion of more than just stocks, bonds, & ETFs. Any additional foreign property, like a holiday home outside Canada, for example, will impact your tax situation. Talk to an expert!

On the other hand, there is nothing wrong with investing in Canadian listed ETFs while you learn more about investing on foreign exchanges & in other currencies. It is a little less work to stick with the loonie. And the end result here was not too far behind the American equivalent. Many investors stick with Canadian listed ETFs, while still getting the necessary foreign exposure. There are also currency hedged ETFs that can help offset those currency fluctuations. But that’s a conversation for a another day.

Just remember that things would begin to reverse in the above chart, if the loonie were to gain in value against the US dollar going forward. In other words, VOO would then start looking better when charted against VFV. In the first 6 months of 2025, for example, VOO is up about 5%. While VFV is essentially flat. The real value of both is still close to the same. But the numbers are different due to a weakening US dollar this year, making VOO look better over this different timeline. This is more about how the numbers look, it’s not that the value is substantially different. Looks can be deceiving, eh!

If you want to learn more about saving & investing from the ground up, I’d like to suggest that you check out Double Double Your Money, available at your local Amazon store.

Important – this is not investing, tax or legal advice, it is for entertainment & conversation-provoking purposes only. Data may not be accurate. Check the current & historical data carefully at any company’s or provider’s website, particularly where a specific product, stock or fund is mentioned. Opinions are my own & I regularly get things wrong, so do your own due diligence & seek professional advice before investing your money.
DIY Investing or Work With a Financial Advisor?

Good old-fashioned financial advice.
But at what price?

DIY investing can drive you a little crazy. Do you like the crazy? Are you enjoying the work that comes with portfolio management? Some of us do! But it gets a little more challenging when we need to withdraw money during retirement. And will a surviving spouse be able to carry on with the crazy portfolio in the event the “money manager” departs first? Are you a good DIY investor? Or would you do better with an advisor?

There is an easy way to figure out if you should consider paying a fee to have a professional manage your portfolio & the retirement cashflow stream for you.
And it’s this …

Compare your DIY portfolio performance against an equivalent ETF. We all need a “benchmark” to check our portfolio against. If you’re 100% in globally diversified stocks, for example, compare your portfolio performance to that of one of the XEQT, ZEQT, VEQT all-equity ETFs. If you’re in a 60/40 stock & fixed income mix, compare your DIY portfolio performance against XBAL, ZBAL, or VBAL. Are you buying a mix of Canadian & US large-cap stocks? Then compare that to an appropriately allocated portfolio of VFV & XIU ETFs. A portfolio filled with way too many stocks & ETFs might also be usefully compared against one of the all-in-ones. If your portfolio performance lags its benchmark by 1% or more, you might want to consider handing it over to a financial manager.

As an aside, since some of these all-in-one funds are so new, you may need to break them down into their constituent ETFs to usefully use them for benchmarking over longer time periods. The longer the history, the more useful the insights.

I’m using 1% here because many financial advisors charge an annual 1% of portfolio value as a fee for managing a portfolio. Is that fee worth it? Get the advisor’s performance history & compare that to an equivalent benchmark ETF too. Their recommended portfolio should only lag the return performance of those ETFs by the 1% fee. If they meet that requirement and if your self-managed portfolio was lagging by more than 1%, you could be getting better results by paying the advisor the 1% fee. As a bonus, you’ll have less work & an advisor who will tell you that everything will be okay when the markets are imploding. Hand-holding is included in their fee! For retirees, the advisor may also plan the income strategy & tax-efficiently manage the cashflow for you, across all accounts. You might even get some estate planning advice along the way. If you have a good advisor, they can deliver a lot of value. Even if they underperform the market average by the amount of the fee they charge.

Can you find an advisor that will consistently beat, after fees, the market or benchmark returns? I don’t know, but be sure to review their data supporting this opinion very carefully. And not necessarily against the benchmark provided by the advisor.

Unfortunately, it can be pretty challenging to tell if an advisor is any good. And those investors who are most challenged by DIY investing will also be challenged by the process of choosing a good advisor. We all like to believe we have the best doctor taking care of our health. In reality, most of them will be closer to average than exceptional. Fortunately, there are minimum standards & qualifications that we hope will ensure an adequate level of service from these professionals. The same is only variably true for financial advisors. Because the qualifications for calling yourself a financial advisor in Canada are variable. Some advisors are closer to being a product salesperson. And while some feel or profess a fiduciary responsibility, it is not a legal duty or obligation for many. They cannot just take your money & head off to a beach somewhere, but they may be putting their own, or their company’s, interests just slightly ahead of yours when it comes to investment choices. Even if only subconsciously.

Of course, a good salesperson will make you feel better about the relationship you are getting into. And that’s not a bad thing. But you also need an advisor who can at least deliver average market returns for a broadly diversified portfolio. Minus the fees. And you do need to know exactly how much you’re paying for whatever services & products are being recommended! There may be advisory fees and product fees, check carefully.

If you are a balanced 60/40 style investor, what would you think of paying an advisor to put all your money into ZBAL? Or maybe 60% into XEQT, with the other 40% into a couple of bond & HISA-type ETFs? We sometimes resent paying for simplicity. Advisors know this & are less likely to present you with such a simple portfolio solution. After all, if things are that simple, why would we need an advisor!
Yet, in DIY mode, we sometimes struggle to follow the simple path ourselves. Instead, we prefer to work hard creating a portfolio that underperforms!

Of course, that simple solution might not be the ideal path for everyone. There may well be good reasons for some investors to pursue a lower volatility strategy, a higher income strategy, or whatever. But it is still useful to compare the total return on our own portfolios against those of low-cost, market index ETFs.

Robo-advisors are trying to bridge the gap between the advisory space & DIY, typically for about a 0.5% fee premium, in addition to ETF fees. I love the idea but it feels like you’re paying the added fee for the robo to pick the same ETFs that are in the all-in-one ETFs. Like some human services, they can fancy it up with one or two more esoteric picks. So you feel like you’re getting something extra for your money. But you generally won’t get the more valuable hand-holding that comes with the more expensive advisory services. Maybe AI will help with this down the road. But AI has been around for a lot longer than current market noise suggests & it hasn’t happened yet. Some robo-services do include human phone support. That might develop & grow into something more valuable going forward.

Isn’t there scope for fee reduction on the human advisory side too? Or for a service with a far more rapidly declining tiered fee-structure for larger portfolios? Are there any low-cost advisors out there? Shouldn’t there be more advisors competing with the 0.5% fees of the robo-advisors. Simpler portfolio advice & management should come with lower fees, no? I’m okay with portfolios constructed with low cost index funds. For some investors, the greater value may be more in managing asset location (what ETF goes in which account) & retirement cashflow. Some advisors include financial planning, a valuable service too. But can it be done for a 0.5% fee? Or less?

I realise that someone else’s job always looks easier than it really is from the outside. But I think financial advisory (& real estate) fees are very expensive in Canada. Particularly for the cookie-cutter portfolios offered by some companies. I’m totally okay with the right cookie-cutter portfolio, I just don’t want to pay through the nose for it. High fees are an ignorance premium being levied on a population that didn’t get this kind of knowledge coming through our educational system. And our schools still don’t prepare kids for the digital environment that now makes it far easier for the DIY investor to learn things the hard way. Fees will likely drop over time, as education & AI combine to work at improving the competitive landscape. Though in traditional Canadian fashion, it’ll probably drag out for a long time yet. And some of us older folk might not live long enough to benefit! 🤪

Regardless of the path we choose, it’s worth occasionally benchmarking our portfolio performance against a low-cost, well-diversified, ETF portfolio. One that approximately matches our portfolio’s asset allocation. Benchmarking can provide insight on how decent a job we’re doing with our investing strategy. And if we’re not doing such a good job ourselves, it may be worth talking to a financial advisor. But if you still find the idea of paying an advisor distasteful, then you’d better figure out how to learn to do it better on your own. Or maybe just use the benchmark ETFs instead!

If you want to learn more about saving & investing from the ground up, I’d like to suggest that you check out Double Double Your Money, available at your local Amazon store.

Important – this is not investing, tax or legal advice, it is for entertainment & conversation-provoking purposes only. Data may not be accurate. Check the current & historical data carefully at any company’s or provider’s website, particularly where a specific product, stock or fund is mentioned. Opinions are my own & I regularly get things wrong, so do your own due diligence & seek professional advice before investing your money.
Getting Started with Investing

The Right Basket of Market Index Funds!

We needed to choose some wall & floor tiles when we bought our last new house. The builder worked with a local tile shop & we were sent there to make our selections. We spent several hours driving ourselves nuts. We were totally frustrated & depressed when we left. After three hours, the staff were relieved to see us go. And we still hadn’t chosen anything! Worse, we’d left the store in a mess. Tiles were spread across half the showroom floor. There were so many to choose from, we just couldn’t make up our minds. I called the store next morning & asked them to lay out about a dozen choices that were mainly black & charcoal. We went back & made our selections from the samples laid out. And we were on our way within ten minutes. Job done. Once we’d decided on a general colour theme, limiting the choices made it far easier to choose.

Investing can be a bit like that for new investors. There are too many choices. Should you invest in stocks or ETFs? For just about all beginning investors, the better choice is ETFs. But, on the Canadian exchange, I think there are more ETFs than stocks now. So which ETFs should you invest in? There are actively managed funds & those that passively track market indices or broad markets. Since, after fees, most professionals can’t beat broad market & index funds, most of the time, the correct answer for most of us is broad market or index funds. Now you are down to the black & charcoal tile scenario! All you’ve got left to do now is figure out which market funds to go with. Fortunately, the fund providers have made this easy for us these days. Not only have they reduced the selection of tiles we need to look at, they’ve put them all in one shopping cart for us.

Many fund providers in Canada offer a globally diversified basket of market index funds that cover the US, Canadian, developed, & emerging markets. The big three providers in Canada, Blackrock, BMO, & Vanguard, offer XEQT, ZEQT, & VEQT, respectively, for this very purpose. You still have to choose one. But the good news is that it doesn’t matter which one you choose, they’re virtually identical. If you want to feel better about it, choose one for your TFSA & a different one in your RRSP. Draw your choices out of a hat, if you like. You are now invested in broad market index funds across the globe. Make your initial investment in these funds & continue to add to them with every paycheque. Job done!

The online noise might suggest you do something differently. For example, the S&P 500® funds, like Vanguard’s VFV, have done phenomenally well for the past decade or more. The American market has crushed the competition. Investors are drawn towards whatever is doing well. That drives the price up. To be fair, there are worse things you could do than get into the US market. AI has a lot of allure these days, for example. However, it is worth remembering the lessons of history. If you’d invested in an S&P 500® fund back in 2000, you’d find yourself with about the same amount in your portfolio after ten years. Yes, today’s hot index created no wealth for a full decade back then. While the Canadian index about doubled over that same period. The Japanese market tumbled from its all time high in 1989. It took 34 years to get back to that high. Even “good” broad market indices can sometimes hurt if you take a narrow focus. Especially over shorter timelines. These global equity funds have all the markets. Including an overweight to the American market. You’re not missing out on what the American market offers, you are just diversifying more. The American market may continue to outperform. But that is still a narrow bet, with an uncertain outcome. Warren Buffett has the confidence & skill to go in harder on more winners than losers. And he loves the American market. But he tends to think in far longer investing timelines than the rest of us. These equity funds are globally diversifed. Diversification is considered the only free lunch in the investing world. And this global approach is a good investing appetiser for a novice investor.

Look, you might not shoot the lights out with one of the above funds. Or at least, not quickly. But you might have a decent chance of growing your wealth over time. Start out this way until you learn more. And when you learn more, you might even decide this is still the best approach for you. Trying to pick the winners, either stocks or narrowly focused ETFs, or trying to pick next year’s winning market, depends more on luck. And good luck with that!

If you invest in one of these funds, & if you continue to add to your investment with a little piece of every paycheque, you’re still not out of the woods. Because your investment will tumble anyway. It’ll go down 5% regularly, but it can also crash 10 or 20%, from time to time. Maybe even 50% or more on rare occasions. What will you do when that happens? What you should do is keep on investing your regular contributions. Buying more of the good stuff when it’s on sale will help grow your long-term wealth even more. Those periodic tumbles are a natural part of the process. Investing is a long game. If you are 30 today, you have 35 years to go to retirement at 65. You might have another 30 years of retirement to get through. That’s a 65 year investing timeline. Historically, the longer the investing timeline, the lower the risk of loss. But the risk of volatility is always with us on the journey. And it’s tough to weather short-term volatility. That’ll be one of the most challenging lessons to learn along the way. While past performance has no bearing on what the future might hold, it’s all we’ve got to go on. Markets have always recovered & gone on to new highs. And if we ever reach a point where global markets fail to grow over time, we’ll have a whole other set of problems that our investments likely won’t fix. Instead of an emergency fund, we’ll need a farm in the wilderness!

Investing is tough, but these globally diversified funds make it easier to get started. And for young investors, getting started early is important. The best education comes from having something invested. And with these funds, you won’t be paralysed trying to choose something from everything available. Because you’ll have a little bit of everything in your shopping cart.

The tiles turned out great, btw!

If you want to learn more about saving & investing from the ground up, I’d like to suggest that you check out Double Double Your Money, available at your local Amazon store.

Important – this is not investing, tax or legal advice, it is for entertainment & conversation-provoking purposes only. Data may not be accurate. Check the current & historical data carefully at any company’s or provider’s website, particularly where a specific product, stock or fund is mentioned. Opinions are my own & I regularly get things wrong, so do your own due diligence & seek professional advice before investing your money

DIY Financial Planning … Is it for You?

Retirement Planning Made Easy!

I’m jumping the gun on this one, but I’m so excited to have stumbled across this financial planning tool that I want to share it with you now. Funny enough, Microsoft’s Copilot chatbot introduced me to this. I asked Copilot to help with a financial plan & after providing some insights & encouragement, the first link it provided was to planeasy.ca. This led me to their financial planning platform adviice.ca. While I’ve only played with it for a few hours yet, I’m really excited about what these guys are doing. And what this platform can do for DIY investors who are also doing DIY financial planning.

One of the drivers for DIY investors to do the DIY thing is our frugal nature. We want to save on investment & advisory fees so that we keep more of our money. That may, or may not, work out well for us, but we just can’t escape the desire to be frugal. This frugal nature also extends to financial planning. Though many DIY investors recognise the value of a financial plan, we tend not to want to pay the fee for having a plan done professionally. And no wonder, it’s not difficult to find fees in the two to five thousand dollar range for having a single financial plan prepared by a professional. Despite the value, that’s still a lot of coin for a one-shot deal. I’m not sure what plan revisions would cost in subsequent years, but it’s fair to assume that as time goes by & circumstances change, it probably makes sense to have the plan updated periodically.

Enter Adviice.ca!

If you’ve watched YouTube® videos on financial planning, you’ll have seen them use software for those sexy charts & graphs that are easily modified for viewing different scenarios. We know we want this, but the software isn’t available to non-professionals in many cases. And some of us are unwilling to pay the price for the professional to do a plan. The Adviice.ca platform costs $9 for a 30 day trial. And $9 a month if you decide to keep the subscription. At these prices, that’s almost 28 years of DIY financial planning for the same cost as one $3,000 plan! There are so many threads to weaving an accumulation or retirement plan. It is very difficult to do it on a notepad or with spreadsheets. Adviice does the calculation grunt work in the background & shows the results in an easy-to-read visual format. It’s also updated to reflect current details on taxation, government income streams, etc. At this point, I haven’t played with the platform for long enough to write a review. Frankly, I’m not qualified to do a real review anyway. The best I could do is provide a DIY appraisal of what I’ve found. However, this post is more about my early enthusiastic reaction to finding it & using it.

Within 2 hours of signing up for this platform, I had a rough-tuned retirement plan done. Much of that time was spent inputting the foundational data. It took another couple of hours to learn enough about how it worked to improve on the first pass. This particular plan embraces a situation that covers another three or four years of working, reviewing different RRSP drawdown strategies, looking at the tax implications of different withdrawal rates across different account types, & so on. I still have much to learn & a lot of fine-tuning to do, but I think I’ve got a pretty respectable financial plan pulled together already. Now the beauty of this is that you can spend as long as you want fine-tuning a plan. Or, to avoid the law of diminishing returns, you can book a one hour session with an advisor at Planeasy, or with other professionals using the platform. You can do this right within the Adviice platform. And for only $499! Or you can book a more comprehensive package for $1,999.00, which could include multiple retirement scenarios, additional tuning sessions, etc. The beauty of this offering is that you can do the DIY thing at a low cost, but then you can add some professional assessment at a lower price than the typical financial planning service might cost. Along with pandering to the hands-on thing favoured by many DIY folk, this could be a cost-effective combination of DIY & professional advice.

Rather than share screenshots, which won’t capture the full scope of what this platform really does, here’s a link to a PlanEasy YouTube® video that covers one example of doing a retirement plan for a couple. It captures a lot of the features & functionality of the system. If you’ve watched financial planning videos in the past, you’ll find a lot you can relate to in this. This clip shows the software with the green PlanEasy branding, mine has the blue Adviice branding, but is otherwise identical. Though there may be some additional features on the latest version. It’s not yet a perfect solution for all scenarios. I’d like to try scenarios where I pass away earlier than my spouse, for example. You can work around most of these limitations by manually adjusting the data columns, but it looks like they are working on improving the functionality & adding features on an ongoing basis. I joined their Reddit® group (r/adviice) where you’ll see feature requests & the company’s responses to these. They are really quick to respond to questions.

The biggest limitation to the client version that I’ve seen, so far, is that we can only create one foundational data set. In other words, short of starting over, we can only do our own plan, for a single or a couple. And that’s fair enough. The advisors pay more & can obviously prepare plans for multiple clients. For those who take advantage of a session with an advisor, the advisors can then use our base plans to add their professional input on top of ours. I guess part of the reason we can get the lower cost professional oversight is because we have already done the work to build the foundational data set. We can still, however, create multiple scenarios based on our own foundational data set. That allows us to explore different accumulation & withdrawal strategies, & so on.
The other limitation is that we cannot create reports. Those are delivered to us after a session with an Adviice advisor. That too is fair. It would be possible to change the foundational data to create reports for others if this was open. Just doing the DIY thing for ourselves, we can get all the relevant info right on the screen. And we can export the plan’s data, for those who want to play with the numbers in a spreadsheet. The reports are not essential for getting value from this software.

Bottom line is that I think this is the first affordable solution that is accessible for Canadians who want to be more involved in creating their own financial plan. Not only is it more affordable to begin with, but it may offer access to professional planning & fine tuning at a more affordable price too. It is a really smart product approach from this company. I think they will find many takers at $9 a month that might otherwise never have spent a penny on financial planning. And I think many of those takers will avail of the tune-up sessions with a professional advisor. And there will be those who will take advantage of the larger, more comprehensive professional support packages too. I hate this way-overused phrase, but this product has all the feel of one of those really good win-win solutions!

If I’m sounding like I work for these guys, I apologise, but I have absolutely no affiliation. I found it last weekend & I ponied up the $9 within 10 minutes of reading about it. Within an hour of playing with it, I knew this was going to be an enjoyable experience. When I compare the number of hours I spend with calculators & spreadsheets trying to do all this, Adviice is a great option for me. However, learning anything new does require some brain activity. And it might not be suitable for everyone. Of course, we all know that we need to challenge our brains as we age. And learning to use this will certainly exercise the brain.
In my case, that might be a bonus! 😜

Despite my enthusiasm, I would also strongly caution against using this as the total solution to a problem that you might not fully understand. If you don’t know enough to have confidence in your current DIY financial plan, you might not know enough to understand if the results produced by Adviice are good enough to live by. Particularly when it comes to depending on a plan that needs to survive your retirements years. I know I’ll enjoy playing & refining a plan with these tools going forward. But I will also take advantage of a one hour session with a professional down the road. Just in case I’ve screwed it up.
Please be careful here!
It may turn out that this product is not suitable for you. But if you enjoy doing this kind of thing, & if you are spending a lot of time with spreadsheets & online calculators, I highly recommend investing the $9 to test drive it.

While I have focused on the older demographic in the course of this conversation, this is also of potential value for the young accumulator.
At long last, there is almost an app for this stuff! LOL

A more recent update on using the Adviice.ca platform can be found at DIY Financial Planning… An Update

If you want to learn more about saving & investing from the ground up, I’d like to suggest that you check out Double Double Your Money, available at your local Amazon store.

Important – this is not investing, tax or legal advice, it is for entertainment & conversation-provoking purposes only. Data may not be accurate. Check the current & historical data carefully at any company’s or provider’s website, particularly where a specific product, stock or fund is mentioned. Opinions are my own & I regularly get things wrong, so do your own due diligence & seek professional advice before investing your money.
Compound Growth or High Yield?

Wish I’d stayed awake for that class!

Compounding confounds & confuses the best of us sometimes. It feels like having a bigger yield to DRIP should work better than waiting for the share price to grow, right? After all, turning on the DRIP on a higher yielding ETF means we’re buying far more shares with every dividend or distribution payout. And that’s true, we are buying more shares with a bigger yield. But that does not mean that it outpaces the compound growth that happens within the share price of a lower yielding fund. Compounding is compounding, regardless of where it occurs. And in a growth stock, or in an ETF filled with growth stocks, the compounding is done by stealth, inside the share price. Not via a distribution. And that does not take away its compounding power. It may even add to it.

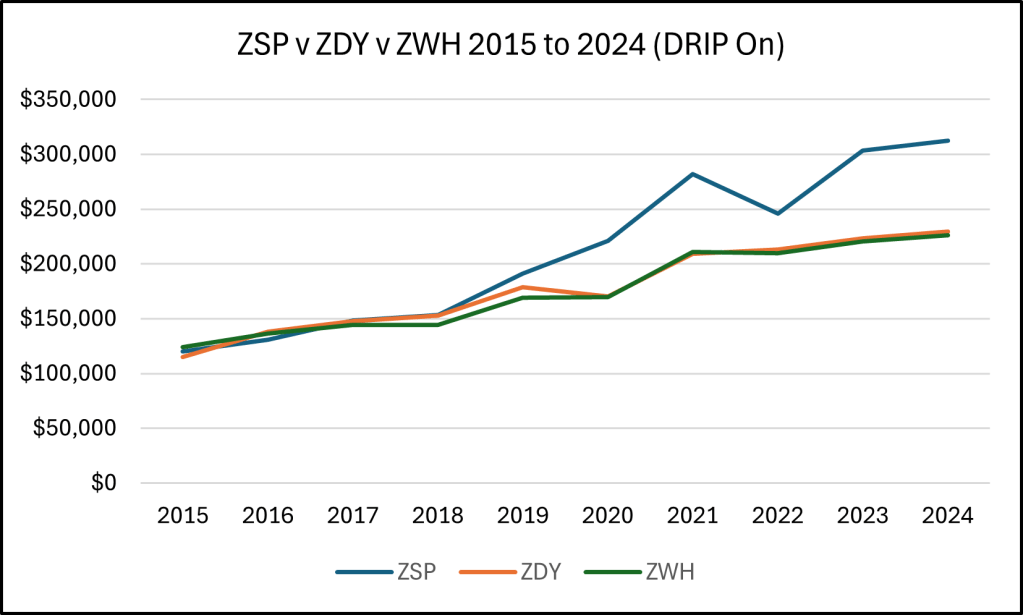
I’m a big fan of their funds, so let’s look at three from the BMO stable for this exercise. ZSP is their S&P 500® Index tracker, ZDY is BMO’s US Dividend ETF, & ZWH is the BMO US High Dividend Covered Call ETF. Here’s what the total returns look like for each, with DRIP on …

I like all three of these funds. ZSP has the lowest yield, typically ranging from about 1.5 to 2%. ZDY has generally floated between 2.5 & 3.5% over the years, while ZWH targets about 6%, give or take a little. The old adage holds true, it’s tough to beat the index fund. ZSP turned $100k into almost $313k over this timeline. ZDY managed to deliver an end value of almost $230k, while ZWH finished at just over $226k. That’s a very respectable comparative return for a covered call ETF.

Despite the positive performance of all these ETFs, the lowest yielding ETF provided the greatest total return. Okay so we know this already, eh? But the confusion tends to increase when we get around to talking about selling shares for income. That strikes fear into the heart of every retiree, even those who can do the math. After all, we’re selling off some of our little geese that lay those golden eggs for us, eh!
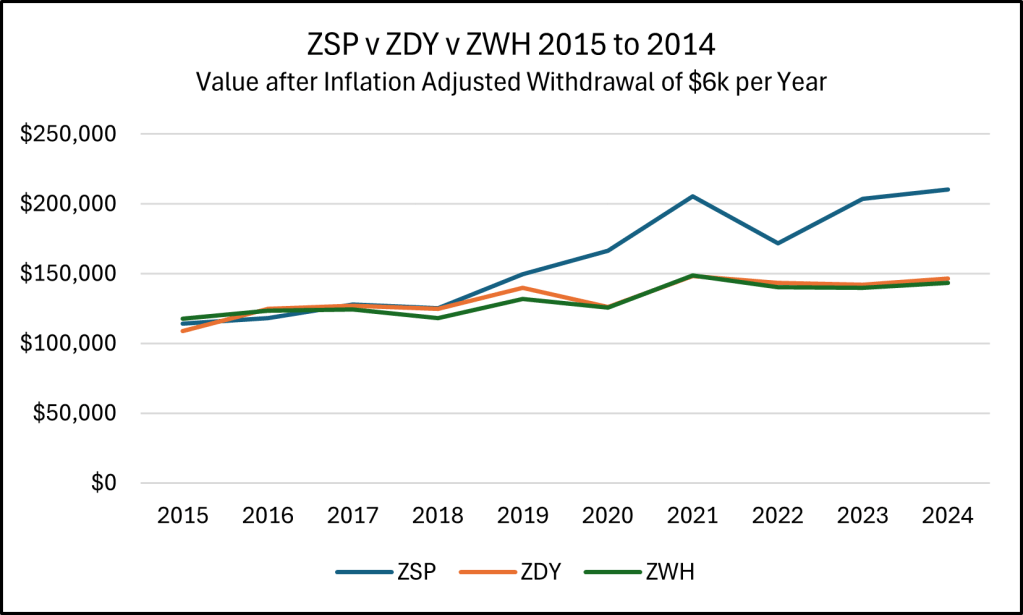
Here’s what that looks like for these three ETFs …

To level the playing field, I used a $6k withdrawal in Year 1 for all three funds, & adjusted for inflation annually in the following years. What remains is each fund’s value after an identical withdrawal. That withdrawal rate approximately matches the higher average distribution rate available from ZWH. ZWH is the only fund of the three that could have avoided selling shares to supply that level of income over this time. However, despite having to sell more shares, the end value of ZSP is $210k. That is significantly more than the $146k remaining in ZDY, & the $143k in ZWH. Despite having to sell more shares to meet the income requirement, the lower yielding funds did better over these years.

Compound growth is just as magical as compound interest or DRIP-driven compound growth. Perhaps it’s even more magical because it doesn’t feel right that you could continue to do better with an ever-declining share count. For better or worse, numbers don’t really care about our feelings!

While the index fund won out over this timeline, there is the potential to have market conditions where a covered call fund might do better. You’ll notice that the ZSP line dips below that of ZWH in 2015 & 2016. Had those market conditions prevailed, ZWH might have continued to lead. They didn’t & ZSP took the lead again. And it stayed ahead through to 2024. While the past doesn’t predict the future, the general tendency for growth in the market suggests that a more growth oriented index fund is likely to outperform over the long haul. Even the bigger downdraft of the index ETF in 2022 wasn’t enough to drag it back down to the level of the other two. During the accumulation phase, it’s all about building the biggest portfolio before retirement. In the decumulation phase, it’s all about portfolio survival!

SOME WORDS OF CAUTION!
This comparison is done over a very short, but generally successful, period of performance for the American markets. I started with a $6k withdrawal rate for this example, to approximate the 6% yield of the highest yielding ETF. But I do not think this is an appropriate withdrawal rate to use for retirement planning. There are reasons why professionals use the 4% Rule in Monte Carlo simulations. It allows for a better hypothetical portfolio survival rate under a greater variety of market conditions. In addition, they may even introduce some additional curtailment or flexibility guidelines to a retirement plan, so that a portfolio survives better during down periods. The caution here is that converting everything to high yield funds in retirement might not provide the best outcome if there are tough times ahead. No question, there are times when it may have worked well. But there is greater exposure to catastrophe if things don’t work so well going forward.
For example, things would have looked very different for a retiree trying to do this starting in the year 2000. Even with an index fund. I used SPY to look at this &, starting with a $6k withdrawal. The portfolio would have gone to zero by 2012. If the withdrawal started at $4k, or 4% of the original portfolio, it will still be delivering income today.
Would a covered call ETF have fared better then? I don’t know, many of today’s funds weren’t around back then. They are too new to assess how they might navigate turbulent markets like those of the lost decade. But having a big yield doesn’t always protect the value of the underlying assets. Choose your retirement strategy with great caution.

If you want to learn more about all this from the ground up, I’d like to suggest that you check out Double Double Your Money, available at your local Amazon store.

Important – this is not investing, tax or legal advice, it is for entertainment & educational purposes only. Data may not be accurate, check the current & historical data carefully at each fund’s website. Opinions are my own, so do your own due diligence & seek professional advice before investing your money.